Dear Reader,
Please find below our summary of the week’s developments in the Indian equity markets.
Indian equities endured a sharply negative week ended October 23, as a surge in crude oil prices on Houthi attacks in Saudi Arabia, a steep correction in mid- and small-cap stocks and persistent foreign institutional investor selling kept investors on edge, with benchmark indices ending lower for the fourth straight session on Friday.
Weekly Overview
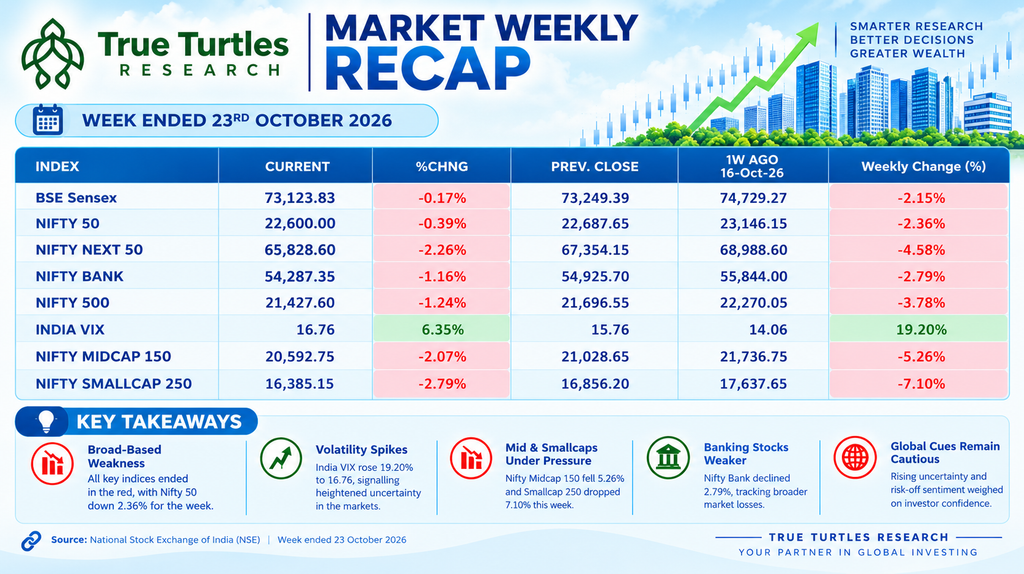
Indian equity markets ended the holiday-shortened week on a broadly weak note, with benchmark indices extending their losses on Friday and the weekly picture turning decisively negative. The Nifty 50 fell 0.39% on the day to close at 22,600.00, while the BSE Sensex slipped 0.17% to settle at 73,123.83. On a weekly basis, the Sensex declined 2.15% versus the previous week’s close of 74,729.27, while the Nifty 50 was down 2.36% from 23,146.15, as selling pressure persisted through all four sessions of the week.
Performance across the broader market was weaker still. The Nifty Next 50 fell a sharp 2.26% on the day to close at 65,828.60 and slumped 4.58% for the week. The Nifty 500 declined 1.24% on the day and 3.78% for the week, while the Nifty Bank index, down 1.16% on the day to close at 54,287.35, ended the week down 2.79%. Among the broader indices, the Nifty Midcap 150 fell 2.07% on the day and 5.26% for the week, while the Nifty Smallcap 250 was the weakest performer, sliding 2.79% on the day and 7.10% for the week — with every major equity index closing the week in negative territory.
Meanwhile, the India VIX rose 6.35% on the day and 19.20% over the week to close at 16.76, pointing to a marked rise in market volatility. Overall, the week was characterised by broad-based selling that deepened into the close, with a sharp correction in mid- and small-cap stocks, rising volatility and a uniformly negative trend across the major benchmark indices.
Weekly Performance of Key Indices
Key Market Triggers
● Crude Surged To A Five-Month High On Houthi Attacks: Brent crude climbed to a session high of around $117 a barrel on Friday, its highest level since early May, after Iran-aligned Houthi attacks across Saudi Arabia, including on energy infrastructure, stoked fears of fresh supply disruption. Saudi Aramco ordered the evacuation of its headquarters in Dhahran on Thursday as fighting intensified, while UAE authorities reported an oil spill from a tanker off Umm Al Quwain. Brent was on course for its third consecutive weekly gain of about 4.4%, even as WTI was set to end the week marginally lower.
● Mid And Small-Caps Bore The Brunt Of The Selling: The broader market corrected far more sharply than the headline indices, with the Nifty Midcap 150 down 5.26% and the Nifty Smallcap 250 down 7.10% for the week. Analysts attributed the pressure to valuation concerns and the unwinding of leveraged positions, compounded by surging crude prices and weak global cues, while the Nifty slipped below its 200-week moving average and market breadth deteriorated sharply.
● Jio Platforms’ Record IPO Drew Strong Demand: Jio Platforms’ ₹30,213 crore initial public offering — entirely a fresh issue and the largest in Indian capital markets history — was open for subscription from October 21 to October 23 at a price band of ₹1,065-₹1,119 per share, after the company raised ₹8,109.85 crore from anchor investors on October 19. The issue was subscribed 22.19 times by the close of bidding, with allotment expected on October 26 and listing scheduled for October 28, even as the mega issue drew liquidity away from the secondary market.
● FIIs Sold For The Tenth Straight Week, But Outflows Moderated: Foreign institutional investors remained net sellers for the tenth consecutive week, offloading about ₹2,697 crore, sharply lower than ₹8,991 crore in the previous week, as the US 10-year Treasury yield eased from 5.36% to around 5%. Domestic institutional investors stayed net buyers for the tenth straight week, purchasing ₹10,942 crore. For October so far, FIIs have sold a net ₹51,466 crore against net DII buying of ₹59,110 crore.
● RBI Minutes Flag Persistent Inflation Risks: The minutes of the Reserve Bank of India’s Monetary Policy Committee meeting, released on October 21, pointed to persistent inflation risks and left room for further monetary tightening, dampening sentiment further. The central bank had raised the repo rate by 25 basis points to 5.50% on October 7, its first hike since 2023, and shifted its policy stance to calibrated tightening.
● Rupee Ended Little Changed Near ₹94.9: The rupee traded in a narrow range through the week, firming to around ₹94.3 per dollar mid-week before giving back most of those gains as crude rallied and foreign fund outflows persisted, and ended Friday near ₹94.9 per dollar, broadly flat from ₹94.96 a week earlier. Easing US Treasury yields helped limit the pressure on the currency.
● Benchmarks Fell In All Four Sessions Of A Holiday-Shortened Week: With trading shut on October 20 for Dussehra, the Sensex lost 876.37 points (1.17%) to close at 73,852.90 and the Nifty fell 1.11% to 22,888.95 on Monday, and the losses extended through Friday, when the Nifty touched an intra-week low of 22,372 before closing at 22,600.00. Brokerage Bernstein also cut its December 2026 Nifty 50 target to 25,000 from 26,000.
Weekly Sectoral Performance
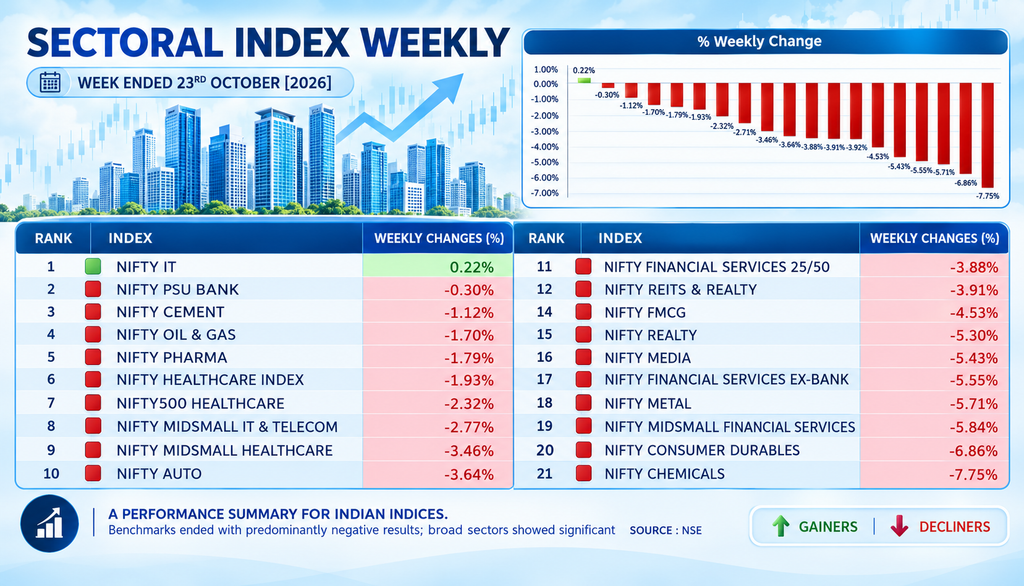
With respect to sectoral performance during the week, losses were widespread, with the Nifty IT index emerging as the only gainer, rising 0.22%. The Nifty PSU Bank index was the best of the decliners, slipping a marginal 0.30%, followed by the Nifty Cement index, down 1.12%, and the Nifty Oil & Gas index, down 1.70%. Healthcare-linked segments saw moderate declines, with the Nifty Pharma index falling 1.79%, the Nifty Healthcare index declining 1.93% and the Nifty500 Healthcare index losing 2.32%.
Conversely, the Nifty Midsmall IT & Telecom index fell 2.77%, followed by the Nifty Midsmall Healthcare and Nifty Auto indices, which declined 3.46% and 3.64%, respectively. The Nifty Financial Services 25/50 and Nifty REITs & Realty indices slipped 3.88% and 3.91%, respectively, while the Nifty FMCG index fell 4.53%. The Nifty Realty, Nifty Media and Nifty Financial Services Ex-Bank indices dropped 5.30%, 5.43% and 5.55%, respectively, while the Nifty Metal and Nifty Midsmall Financial Services indices were down 5.71% and 5.84%. The Nifty Consumer Durables index fell a sharper 6.86%, while the Nifty Chemicals index recorded the steepest decline of the week, falling 7.75%. Overall, it was a broadly negative week for sectoral indices, with IT the lone gainer even as chemicals, consumer durables, financial services and metals bore the brunt of the selling.
(Source: NSE)
Wrapping Up
Indian equities endured a punishing week, as a surge in crude oil prices to a five-month high on Houthi attacks in Saudi Arabia, a steep correction in mid- and small-cap stocks and persistent foreign institutional investor selling weighed on investor sentiment. The Nifty 50 and Sensex ended the week down 2.36% and 2.15%, respectively, while the Nifty Midcap 150 and Nifty Smallcap 250 fell 5.26% and 7.10%, and a 19.20% jump in the India VIX pointed to rising nervousness. Only the Nifty IT index closed the week in positive territory, even as moderating FII outflows and steady domestic institutional buying provided a limited cushion. Markets are likely to remain sensitive to the listing of Jio Platforms’ mega initial public offering on October 28, the US Federal Reserve’s upcoming policy decision and the situation around the Saudi-Houthi conflict. Going forward, investors are likely to closely monitor crude oil price movements, developments in the Middle East, the ongoing Q2 earnings season, foreign institutional investor flows and the rupee’s trajectory for further direction in the market.
