
Dear Reader,
Please find below our summary of the week’s developments in the Indian equity markets.
Indian equities delivered their strongest weekly gains in six months in the week ended October 16, as a historic rally in IT stocks and a sharp recovery in the rupee outweighed elevated crude oil prices, persistent foreign institutional selling and a global selloff in AI-linked stocks, with a firm session on Friday taking the benchmark indices to their highest closing levels in over three weeks.
Weekly Overview
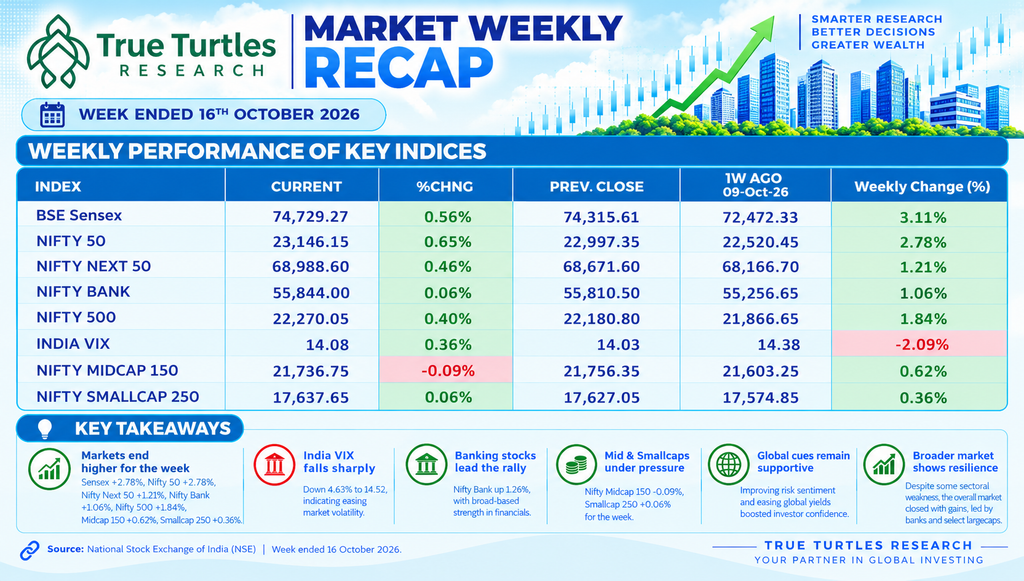
Indian equity markets ended the week on a strong note, with benchmark indices extending gains for a second straight session on Friday and posting their sharpest weekly advance in six months. The Nifty 50 rose 0.65% on the day to close at 23,146.15, while the BSE Sensex gained 0.56% to settle at 74,729.27. On a weekly basis, the Sensex surged 3.11% and the Nifty 50 advanced 2.78% versus the previous week’s close, as a sharp rally in IT stocks led the move higher.
Performance across the broader market was similarly positive, though more measured. The Nifty Next 50 rose 0.46% on the day to close at 68,988.60 and gained 1.21% for the week. The Nifty 500 advanced 0.40% on the day and 1.84% for the week, while the Nifty Bank index, up 0.06% on the day to close at 55,844.00, ended the week up 1.06%. Among the broader indices, the Nifty Midcap 150 slipped 0.09% on the day to close at 21,736.75 — the only major index to close lower on the day — though it still ended the week up 0.62%, while the Nifty Smallcap 250 edged up 0.06% on the day and gained 0.36% for the week, lagging the large-cap indices.
Meanwhile, the India VIX rose marginally by 0.36% on the day to close at 14.08, but fell 2.09% over the week, pointing to a modest easing in market volatility. Overall, the week was characterised by broad-based gains led by a sharp rally in IT stocks, with large caps outperforming the mid- and small-cap segments and volatility cooling over the week.
Weekly Performance of Key Indices
Key Market Triggers
● IT Stocks Stage Historic Rally On Earnings Recovery: The Nifty IT index surged over 10% for the week, its sharpest weekly gain in nearly 18 years, as TCS, Infosys, HCLTech and Tech Mahindra rose between 13% and 18% on improving earnings and renewed investor interest in traditional software services names amid a selloff in US AI-linked stocks. HCLTech reported a 21.2% rise in Q2 net profit to ₹5,132 crore and raised the lower end of its FY27 revenue growth guidance to 2.5%, while Tech Mahindra’s profit jumped 32.7% to ₹1,586 crore and it announced a 1:1 bonus issue, driving its strongest single-day gain since March 2020.
● Crude Oil Surged To Highest Since May On Hormuz Attacks: Brent crude settled at $109.86 a barrel on Friday, its highest level since May, gaining about 4.9% for the week as attacks on at least nine vessels near the Strait of Hormuz since October 11 cut Gulf crude flows to roughly 68% of pre-war levels. US WTI crude jumped over 10% for the week to about $101 a barrel, while the International Energy Agency’s 20-million-barrel diesel release did little to ease supply worries.
● Rupee Posts Best Week In Seven Months: The rupee appreciated about 1.9% to close near ₹94.96 per dollar on Friday, its strongest weekly gain in seven months and its first close below ₹95 since September 8, after ending the previous week at ₹96.73, just short of its record low of ₹96.96. The recovery was driven by RBI measures, including a special dollar window for oil marketing companies, tighter forex derivative rules and a sharp cut in the limit for dollar purchases without underlying exposure, even as elevated crude prices and foreign outflows capped gains.
● Forex Reserves Slide Further From Record High: India’s foreign exchange reserves fell by $8.58 billion to $726.03 billion for the week ended October 9, as per RBI data released on Friday, following a $12.95 billion drop in the previous week. Reserves are now about $59.7 billion below the all-time high of $785.71 billion touched in the week ended September 4, with the latest decline led by a $7.14 billion fall in foreign currency assets and a $1.32 billion fall in gold holdings.
● Retail Inflation Jumps To Highest Since October 2024: India’s CPI inflation rose to 5.54% in September from 4.83% in August, data released on October 12 showed, above the 5.4% market estimate, with food inflation at 7.74%. The jump, coming days after the RBI’s 25 basis point repo rate hike to 5.50% on October 7 and its shift to a calibrated-tightening stance, strengthened expectations of further rate hikes as the Middle East conflict and weak monsoon-led price pressures feed through the economy.
● Hot US Inflation And AI Selloff Rattled Global Markets: Hotter-than-expected US CPI inflation of 3.7% in September (versus 3.4% in August), released on October 14, pushed the 10-year Treasury yield as high as 5.33%, before a sharp selloff in AI-linked stocks left the Nasdaq Composite down about 4.5% for the week, its worst since June, as chip stocks extended their longest losing streak since 2008. The 10-year yield eased about 15 basis points to 5.10% on safe-haven demand, while traders pared bets on a Fed rate hike at its late-October meeting to around 17% after Chair Kevin Warsh declined to pre-signal the policy path.
● FIIs Stayed Net Sellers As Domestic Investors Cushioned The Fall: Foreign institutional investors net sold about ₹8,991 crore of Indian equities across the sessions from October 12 to 16, including ₹5,285 crore on Thursday alone, before turning net buyers by ₹1,166 crore on Friday, taking October’s net selling to about ₹48,769 crore. Domestic institutional investors bought a net ₹7,813 crore over the same period, while liquidity is likely to be tested next week by the ₹30,213 crore Jio Platforms IPO (price band ₹1,065-₹1,119), which opens on October 21.
Weekly Sectoral Performance
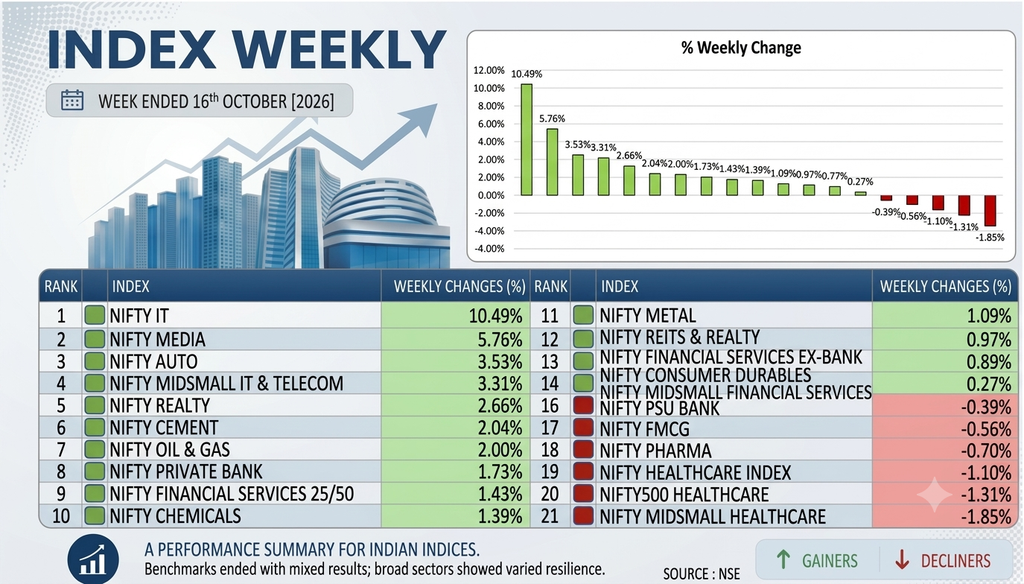
With respect to sectoral performance during the week, gains were broad-based and led by technology and media-linked segments. The Nifty IT index topped the gainers’ chart with a sharp rise of 10.49%, followed by the Nifty Media index, which advanced 5.76%. The Nifty Auto index gained 3.53%, while the Nifty Midsmall IT & Telecom index added 3.31%. Realty and commodity-linked segments also extended gains, with the Nifty Realty index rising 2.66%, the Nifty Cement index adding 2.04% and the Nifty Oil & Gas index up 2.00%. Financials participated in the rally, with the Nifty Private Bank index gaining 1.73% and the Nifty Financial Services 25/50 index advancing 1.43%, while the Nifty Chemicals and Nifty Metal indices rose 1.39% and 1.09%, respectively. The Nifty REITs & Realty, Nifty Financial Services Ex-Bank, Nifty Consumer Durables and Nifty Midsmall Financial Services indices rounded out the week’s gainers with more modest advances of 0.97%, 0.89%, 0.77% and 0.27%, respectively.
Conversely, healthcare and consumption-linked segments bore the brunt of the selling during the week. The Nifty Midsmall Healthcare index recorded the steepest decline of the week, falling 1.85%, followed by the Nifty500 Healthcare index, down 1.31%, and the Nifty Healthcare index, which declined 1.10%. The Nifty Pharma index slipped 0.70%, while the Nifty FMCG index fell 0.56% and the Nifty PSU Bank index declined 0.39%, rounding out the week’s sectoral decliners. Overall, it was a broadly positive week for sectoral indices, with 15 of the 21 indices closing higher, led by IT, media and auto, even as healthcare, FMCG and PSU banks lagged.
Wrapping Up
Indian equities delivered their strongest weekly gains in six months, as a historic rally in IT stocks, a sharp recovery in the rupee and a pullback in US bond yields outweighed pressure from Brent crude climbing back toward $110, continued foreign institutional selling and a global selloff in AI-linked shares. The Sensex and Nifty 50 ended the week 3.11% and 2.78% higher, respectively, even as the India VIX eased to 14.08, though gains were less pronounced in the mid- and small-cap segments. Markets are likely to remain sensitive to further developments around the Strait of Hormuz, the September-quarter earnings season — with HDFC Bank, ICICI Bank and Axis Bank having reported on Saturday — and the opening of the ₹30,213 crore Jio Platforms IPO on October 21, in a holiday-shortened week with markets closed on Tuesday for Dussehra. Going forward, investors are likely to closely monitor crude oil price movements, developments in the Middle East, the Federal Reserve’s late-October policy meeting, the RBI’s next policy signals amid rising inflation, foreign institutional investor flows and the rupee’s trajectory for further direction in the market.
