
Indian Equity Markets — Week Ended October 09, 2026
Dear Reader,
Please find below our summary of the week’s developments in the Indian equity markets.
Indian equities ended the week on a firmer note, with the Sensex up 0.78% and the Nifty 50 up 0.44%, as a sharp Friday rebound more than offset a steep mid-week sell-off triggered by the RBI’s first repo rate hike since February 2023, crude oil prices holding above $100 a barrel and relentless foreign institutional selling.
Weekly Overview
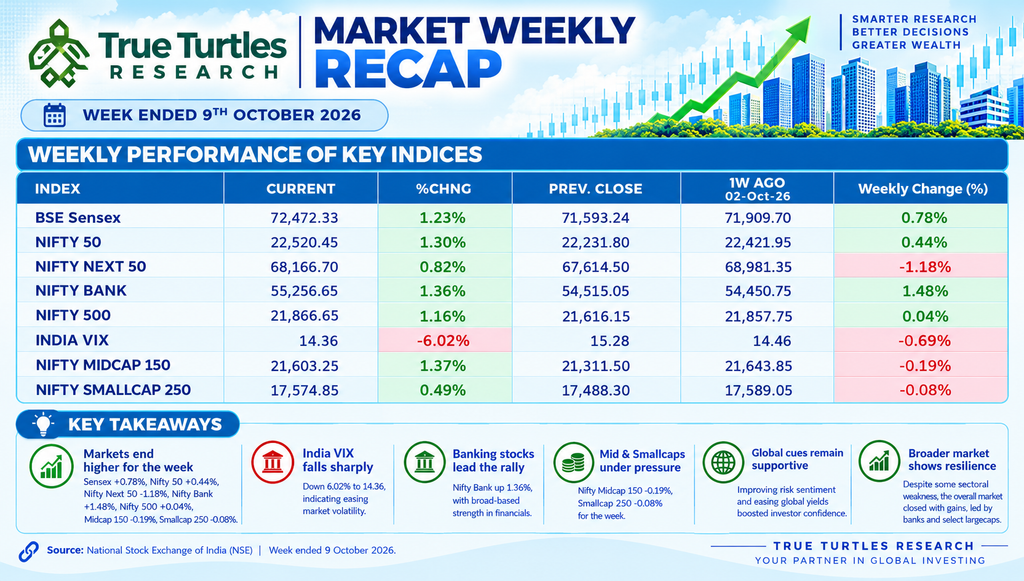
Indian equity markets ended the week on a positive note, with benchmark indices staging a strong recovery in Friday’s session after a volatile stretch. The BSE Sensex rose 1.23% on the day to close at 72,472.33, while the Nifty 50 gained 1.30% to settle at 22,520.45. On a weekly basis, the Sensex advanced 0.78% and the Nifty 50 gained 0.44%, as Friday’s rebound more than offset Thursday’s sharp sell-off, when both indices had fallen over 1.4%.
Performance across the broader market was mixed. The Nifty Next 50 rose 0.82% on the day to close at 68,166.70 but ended the week down 1.18%, the steepest weekly decline among the major indices. The Nifty 500 advanced 1.16% on the day to close at 21,866.65 and was up 0.04% for the week, while the Nifty Bank index, up 1.36% on the day to close at 55,256.65, ended the week 1.48% higher, making it the best weekly performer among the major indices. Among the broader indices, the Nifty Midcap 150 gained 1.37% on the day to close at 21,603.25 but slipped 0.19% for the week, while the Nifty Smallcap 250 rose 0.49% on the day to 17,574.85 and ended the week down 0.08%.
Meanwhile, the India VIX fell 6.02% on the day to close at 14.36 and was down 0.69% for the week, pointing to an easing in market volatility after Thursday’s spike. Overall, the week was characterised by a strong Friday recovery led by banking stocks, with large-caps outperforming mid- and small-caps and the broader market lagging the headline indices.
Weekly Performance of Key Indices
Key Market Triggers
● RBI Hikes Repo Rate By 25 bps, Turns Hawkish: The RBI’s Monetary Policy Committee unanimously raised the repo rate by 25 basis points to 5.50% on October 7, its first hike since February 2023, and shifted its stance to calibrated tightening. The central bank projected FY27 CPI inflation at 5.2% and raised its FY27 GDP growth forecast by 40 bps to 7.1%. The hawkish turn weighed on rate-sensitive sectors and fed into Thursday’s sharp sell-off, when the Nifty slipped to a 21-month low.
● Crude Oil Stayed Above $100 On Strait Of Hormuz Disruptions: Brent crude held above $100 a barrel through the week as repeated tanker attacks near the Strait of Hormuz, with UK officials reporting at least nine incidents so far in October, and a Gulf storm threat kept supply concerns elevated. Brent jumped about 4% on Thursday to roughly $104 before easing to around $103 on Friday, as Iran was reported to be reviewing the US response to its proposal to reopen the Strait, leaving Brent up around 2% for the week.
● Rupee Hovered Near Record Lows: The rupee stayed under pressure amid a strong US dollar, elevated crude prices and foreign outflows, closing at ₹96.88 per dollar (provisional) on Thursday, down 13 paise, before steadying near ₹96.8 on Friday. Suspected RBI intervention helped limit the slide at lower levels.
● Forex Reserves Fall Sharply: India’s foreign exchange reserves dropped by $12.95 billion to $734.61 billion in the week ended October 2, as per RBI data released on Friday, led by a fall in foreign currency assets and a $2.29 billion decline in gold reserves to $106.41 billion. Reserves nevertheless remain about $43.5 billion above their end-March 2026 level.
● FIIs Sell For An Eighth Straight Week; DIIs Absorb The Selling: Foreign institutional investors net sold equities worth ₹30,294 crore during the week, taking their October net selling to ₹39,779 crore, amid elevated US yields and a rotation of global capital towards AI-led North Asian markets. Domestic institutional investors bought ₹30,313 crore over the same period, fully absorbing the foreign selling and supporting Friday’s rebound.
● US Yields Stay Elevated, Wall Street Ends Higher: The US 10-year Treasury yield ended the week near 5.24%, about 5 bps lower for the week, after touching 5.31% on October 5, close to its highest levels since 2002. Softer-than-expected US September payrolls (29,000 jobs) reduced the odds of an October Fed hike, while all three major Wall Street indices posted weekly gains, with the S&P 500 closing Friday at 7,811.5 near its record high.
● TCS Q2 Results Lift IT Stocks: TCS reported Q2 FY27 consolidated net profit of ₹13,884 crore, up about 15% year-on-year, on revenue of ₹73,188 crore, up 11.2%, and declared a ₹12 interim dividend, with annualised AI revenue crossing US$3.1 billion. The results were slightly ahead of estimates, though brokerages flagged margin pressure. TCS shares rose about 5.5% on Friday and helped IT stocks lead the rebound, with the Nifty IT index ending the week 0.95% higher.
Weekly Sectoral Performance
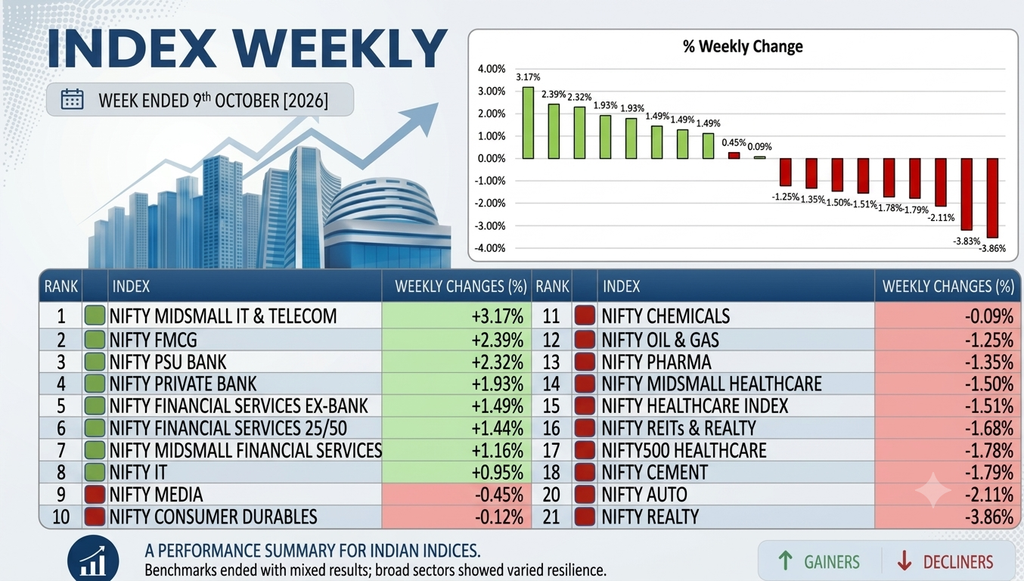
With respect to sectoral performance during the week, gains were led by technology, consumption and financial segments. The Nifty Midsmall IT & Telecom index topped the gainers’ chart with a rise of 3.17%, followed by the Nifty FMCG index, which advanced 2.39%. Banking indices were also strong, with the Nifty PSU Bank index gaining 2.32% and the Nifty Private Bank index adding 1.93%. The Nifty Financial Services Ex-Bank, Nifty Financial Services 25/50 and Nifty Midsmall Financial Services indices rose 1.49%, 1.44% and 1.16%, respectively, while the Nifty IT index rounded out the week’s gainers with an advance of 0.95%.
Conversely, the Nifty Realty index recorded the steepest decline of the week, falling 3.86%, followed by the Nifty Auto index, which slipped 2.11%. The Nifty Cement index declined 1.79%, the Nifty500 Healthcare index fell 1.78% and the Nifty REITs & Realty index lost 1.68%. Healthcare-linked segments remained under pressure, with the Nifty Healthcare and Nifty Midsmall Healthcare indices down 1.51% and 1.50%, respectively, and the Nifty Pharma index falling 1.35%. The Nifty Oil & Gas index declined 1.25%, while the Nifty Media, Nifty Consumer Durables and Nifty Chemicals indices ended modestly lower, down 0.45%, 0.12% and 0.09%, respectively. Overall, it was a week in which IT, FMCG and banking and financial services-linked indices led the gains even as realty, auto, cement and healthcare bore the brunt of the selling.
(Source: NSE)
Wrapping Up
Indian equities ended the week higher after a volatile stretch, as a strong Friday rebound led by banking and IT stocks offset Thursday’s sell-off, which was triggered by the RBI’s first rate hike since February 2023, crude oil prices holding above $100 a barrel and persistent foreign selling. The Nifty 50 gained 0.44% and the Sensex 0.78% for the week, while the Nifty Bank index led the major indices with a 1.48% advance and the India VIX eased to 14.36. Strong results from TCS, steady domestic institutional buying and a pullback in crude prices on Friday provided support, even as the broader market lagged, with the Nifty Next 50, Midcap 150 and Smallcap 250 ending the week lower. Markets are likely to remain sensitive to developments around the Strait of Hormuz and crude oil prices, the trajectory of the rupee and foreign institutional investor flows. Going forward, investors are likely to closely monitor the RBI’s follow-up policy signals, the Q2 earnings season, US bond yields and the Federal Reserve’s next policy decision for further direction in the market.
